Managing money has become increasingly important in 2026. Rising everyday expenses, digital payments, online shopping, changing job markets, and easy access to financial products can make personal money management more complicated.
The good news is that building better financial habits does not necessarily require a high income. Creating a realistic budget, controlling unnecessary spending, building savings, managing debt, and learning basic investing principles can help you work toward your financial goals.
This guide explains practical personal finance tips for 2026 that can help you manage money more effectively.
What Is Personal Finance?
Personal finance refers to how an individual manages their money.
It includes:
Income
Spending
Saving
Budgeting
Debt
Investing
Insurance
Financial goals
Emergency planning
Good personal finance is not about never spending money. It is about making intentional decisions about where your money goes.
Why Personal Finance Matters in 2026
Financial decisions can affect many areas of life.
Better money management can help you:
Handle unexpected expenses
Reduce financial stress
Prepare for future goals
Avoid unnecessary debt
Build savings
Make informed investment decisions
Technology also makes it easier to track expenses, automate savings, compare financial products, and manage accounts digitally.
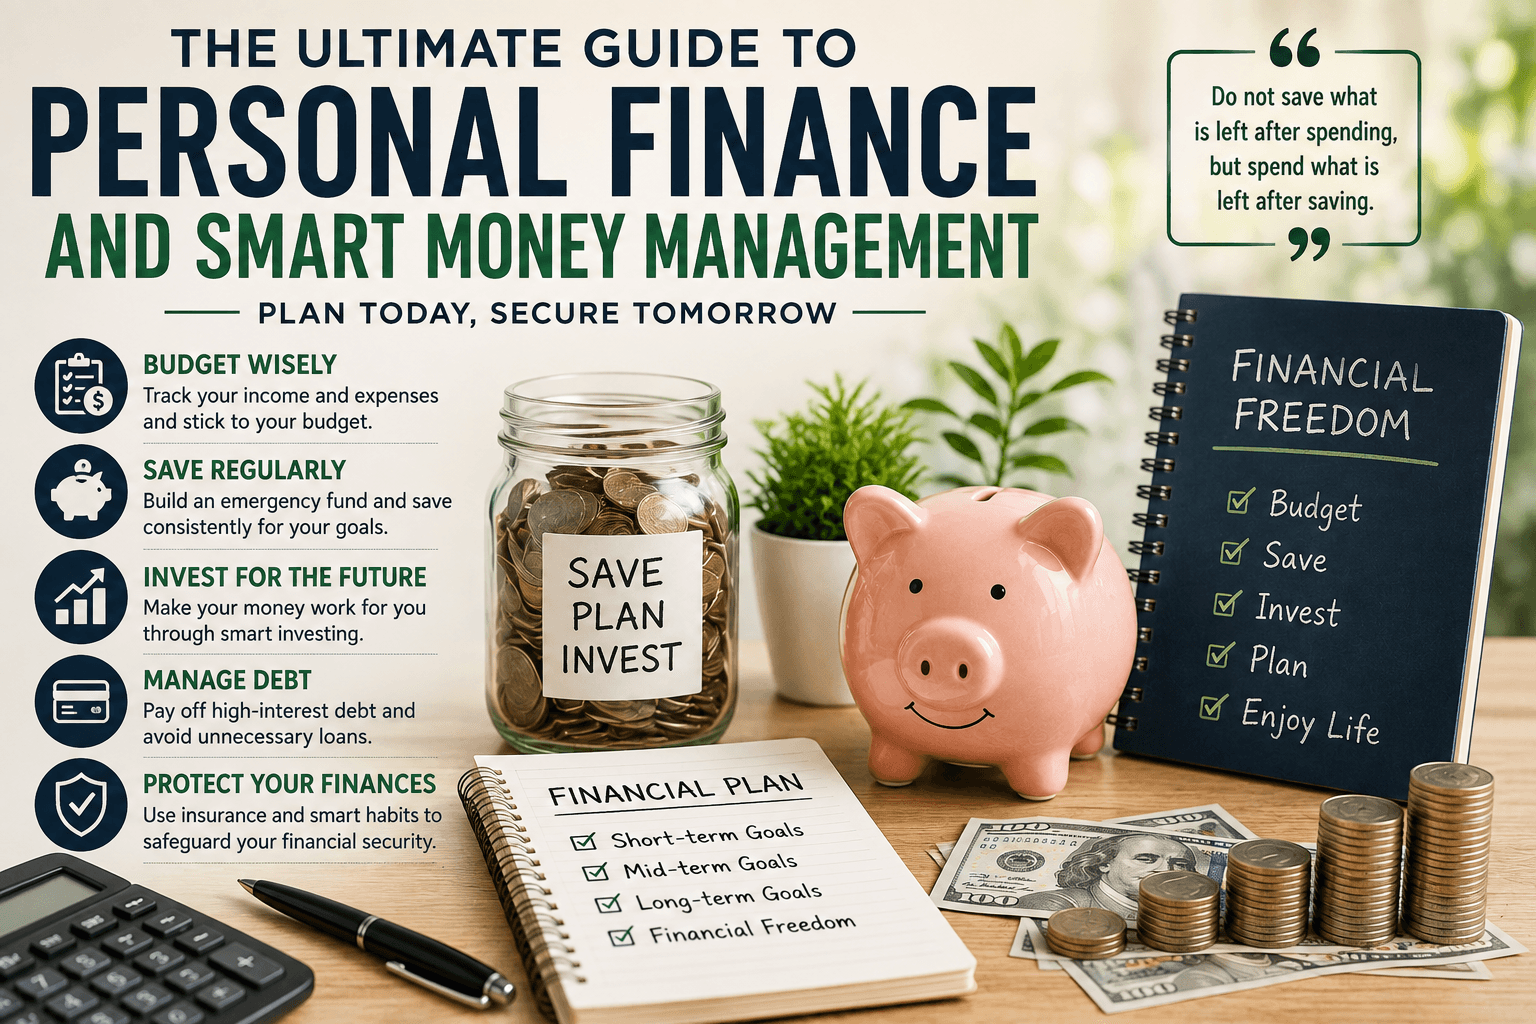
1. Create a Realistic Budget
A budget gives you a clear picture of your income and expenses.
Start by listing your monthly income and then divide expenses into categories such as:
Housing
Food
Transportation
Education
Bills
Entertainment
Shopping
Savings
Your budget should reflect your actual lifestyle rather than an unrealistic target.
Try the 50/30/20 Rule as a Guideline
A commonly used budgeting framework divides after-tax income into:
50% for needs
30% for wants
20% for savings and debt repayment
This is only a guideline. Your personal percentages may need to be different depending on income, location, family responsibilities, and financial goals.
2. Track Your Spending
Many small purchases can add up over time.
Track your spending for at least a few weeks to identify where your money is going.
You may discover recurring expenses such as:
Unused subscriptions
Frequent food delivery
Impulse shopping
Unnecessary app purchases
Expensive convenience spending
Once you know your spending patterns, you can decide which expenses are worth keeping.
3. Build an Emergency Fund
An emergency fund is money kept aside for unexpected expenses.
Examples include:
Medical expenses
Emergency travel
Essential repairs
Temporary loss of income
Unexpected family expenses
The appropriate amount depends on your circumstances. Many financial planners suggest gradually building several months of essential expenses.
If saving a large amount feels difficult, start with a small target and increase it over time.
4. Reduce High-Cost Debt
Debt can become expensive when interest and fees accumulate.
If you have high-cost debt, review:
Interest rates
Minimum payments
Fees
Remaining balances
Paying more than the minimum, when affordable, can help reduce the balance faster.
Avoid taking on new debt simply to fund unnecessary purchases.
5. Separate Needs From Wants
One of the simplest financial habits is learning the difference between something you need and something you simply want.
Needs may include:
Food
Housing
Basic clothing
Transportation
Essential education expenses
Wants may include:
Luxury shopping
Entertainment
Expensive upgrades
Non-essential subscriptions
You do not need to eliminate wants completely. Instead, include them in your budget intentionally.
6. Automate Your Savings
Automation can make saving easier.
If your bank or financial service supports automatic transfers, you may be able to move a chosen amount into savings regularly.
Even a small recurring amount can help create a consistent savings habit.
Example
Instead of waiting until the end of the month to save whatever remains, set aside a planned amount soon after receiving income.
7. Set Specific Financial Goals
A financial goal is easier to follow when it is specific.
Instead of:
“I want to save money.”
Try:
“I want to save a specific amount for education, travel, an emergency fund, or another goal by a particular date.”
Common goals include:
Education
A business
Travel
Emergency savings
A major purchase
Long-term investing
8. Learn the Basics of Investing
Saving and investing are different.
Savings are generally designed for short-term needs and emergencies, while investing is usually focused on longer-term growth and involves risk.
Investment options vary by country and may include:
Stocks
Bonds
Mutual funds
Exchange-traded funds
Real estate
Other regulated investments
Before investing, understand the risks, fees, time horizon, and rules that apply to the specific investment.
9. Understand Risk and Diversification
Every investment involves some level of risk.
Diversification means spreading investments across different assets or investments rather than relying heavily on one.
The appropriate investment strategy depends on factors such as:
Financial goals
Time horizon
Risk tolerance
Income
Existing assets
Never invest money you cannot afford to lose without understanding the risks involved.
10. Take Advantage of Compound Growth
Compound growth occurs when returns generate additional returns over time.
The effect can become more significant over long periods.
For example, if money earns a return and those returns remain invested, future growth can occur on both the original amount and previous returns.
This is one reason starting long-term financial planning early can be useful.
11. Be Careful With Online Shopping
Digital shopping makes spending extremely convenient.
Before buying something, ask:
Do I actually need it?
Is it within my budget?
Did I compare prices?
Am I buying because of a limited-time promotion?
Will I still want it tomorrow?
Waiting before making non-essential purchases can reduce impulse spending.
12. Review Subscriptions
Subscriptions can quietly consume part of a monthly budget.
Review recurring payments for:
Streaming services
Apps
Gaming subscriptions
Cloud storage
Fitness memberships
Software
Cancel services you no longer use.
13. Use Technology for Money Management
Financial technology can make tracking money easier.
Useful digital features may include:
Expense tracking
Budgeting dashboards
Automatic transfers
Spending alerts
Digital statements
Account notifications
However, protect financial accounts with strong passwords, multi-factor authentication where available, and secure devices.
14. Be Careful With Financial Scams
Online financial scams continue to be a major concern.
Be cautious about messages promising:
Guaranteed investment profits
Extremely high returns
Easy money
Urgent payment requests
Fake job opportunities
Suspicious cryptocurrency investments
Never share passwords, one-time authentication codes, or sensitive financial information with unknown people.
15. Build More Than One Income Skill
Depending on your circumstances, developing additional skills can improve your earning opportunities.
Potential skills include:
Writing
Programming
Graphic design
Video editing
Digital marketing
Data analysis
Online tutoring
AI-assisted services
For students, focusing first on education and useful skills can provide a foundation for future earning opportunities.
16. Personal Finance for Students
Students can start learning money management before earning a full-time income.
Useful habits include:
Tracking spending
Saving part of available money
Avoiding unnecessary debt
Learning basic financial concepts
Comparing prices
Setting financial goals
Small habits developed early can become valuable later.
17. Personal Finance for Young Professionals
When you start earning a regular income, it can be tempting to increase spending immediately.
Instead, consider creating a system that allocates income toward:
Essential expenses
Emergency savings
Debt repayment
Long-term goals
Personal spending
The exact amounts depend on your circumstances.
18. Don't Ignore Financial Education
Financial literacy can help you make better-informed decisions.
Learn the basics of:
Interest
Inflation
Taxes
Credit
Debt
Investing
Insurance
Compound growth
Risk
You do not need to become a financial expert overnight. Start with one concept at a time.
19. Review Your Finances Regularly
Your financial situation can change.
Review your budget and goals regularly, especially after:
Getting a new job
Moving
Starting college
Getting married
Starting a business
Taking on new debt
Experiencing a major income change
A flexible financial plan is often more useful than a rigid one.
20. A Simple Personal Finance Plan for 2026
Here is a basic framework:
Step 1: Calculate your income.
Step 2: List essential expenses.
Step 3: Track discretionary spending.
Step 4: Create an emergency savings goal.
Step 5: Pay attention to high-cost debt.
Step 6: Set short- and long-term goals.
Step 7: Learn about suitable investment options.
Step 8: Automate savings where possible.
Step 9: Protect your financial accounts.
Step 10: Review your plan regularly.
Common Personal Finance Mistakes
Avoiding common mistakes can be just as important as building good habits.
Some include:
Spending without tracking
Taking unnecessary high-cost debt
Having no emergency savings
Investing without understanding risk
Following financial trends blindly
Falling for guaranteed-return promises
Ignoring recurring expenses
Using credit for purchases you cannot afford
Final Thoughts
Personal finance in 2026 is about creating a system that helps you control spending, build savings, manage debt, and work toward long-term goals.
You do not need to make dramatic changes overnight.
Start with simple actions: track your spending, create a realistic budget, save consistently, learn about investing, and protect yourself from financial scams.
Over time, small and consistent financial decisions can make a meaningful difference.
20 Frequently Asked Questions
1. What is personal finance?
Personal finance is the management of income, spending, saving, debt, investing, and financial goals.
2. What is the best way to start managing money?
Start by tracking your income and expenses and creating a realistic budget.
3. How much should I save each month?
There is no single amount that works for everyone. Choose an amount that fits your income and expenses and increase it when possible.
4. What is an emergency fund?
An emergency fund is money reserved for unexpected essential expenses.
5. Is the 50/30/20 rule still useful?
It can be a helpful budgeting guideline, but it should be adjusted to your personal circumstances.
6. Should I save or invest first?
Emergency savings and high-cost debt generally deserve attention before taking significant investment risk. The right order depends on your circumstances.
7. What is compound growth?
Compound growth occurs when returns remain invested and can generate additional returns over time.
8. How can I reduce unnecessary spending?
Track expenses, review subscriptions, compare prices, and pause before making impulse purchases.
9. How can students learn personal finance?
Students can begin by learning budgeting, saving, spending, interest, debt, and basic investing concepts.
10. What is diversification?
Diversification involves spreading investments across different assets or investments to avoid excessive concentration in one area.
11. Is investing risky?
Yes. Investments can lose value, and the level of risk varies between different investments.
12. How can I protect myself from financial scams?
Avoid guaranteed-profit promises, verify financial offers independently, and never share passwords or authentication codes.
13. Should I use a budgeting app?
A budgeting app can be useful if it helps you consistently track spending and manage your financial goals.
14. How can I save money on a low income?
Focus on essential expenses, reduce unnecessary recurring costs, set small savings targets, and increase your earning skills when possible.
15. What financial skills should young people learn?
Budgeting, saving, debt management, investing basics, taxes, financial security, and understanding interest are useful skills.
16. Why is financial literacy important?
Financial literacy can help people understand financial products, risks, costs, and everyday money decisions.
17. How often should I review my budget?
A monthly review is a practical starting point, with additional reviews whenever your income or expenses change significantly.
18. Should I avoid all debt?
Not all debt has the same cost or purpose. The important factors include interest rates, fees, affordability, and the reason for borrowing.
19. Can technology improve personal finance?
Yes. Digital tools can assist with expense tracking, budgeting, saving, alerts, and financial organization.
20. What is the most important personal finance habit?
Consistency is important. Regularly tracking money, saving, controlling unnecessary spending, and reviewing goals can help build better financial habits over time.