Introduction
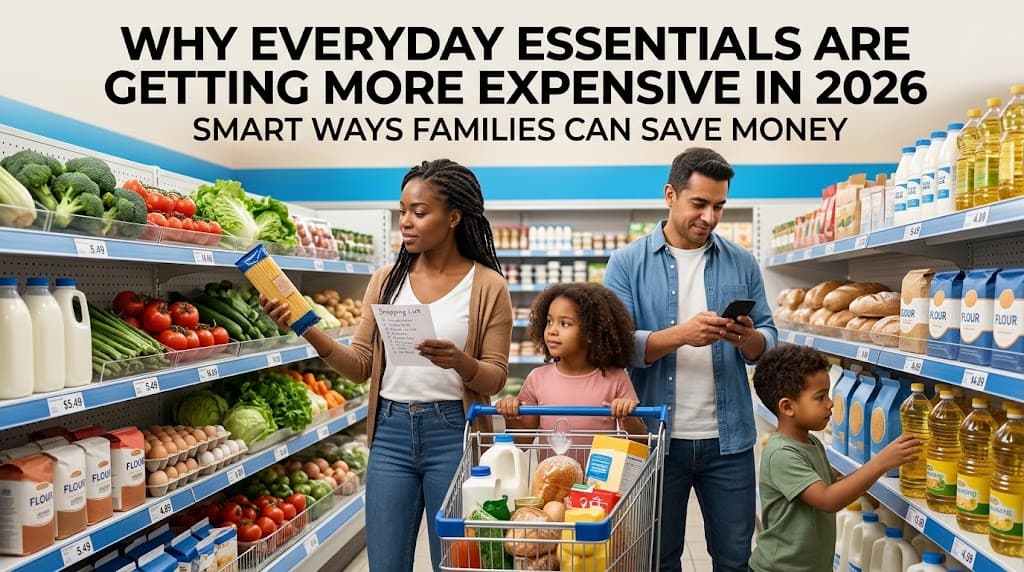
Everyday essentials such as groceries, electricity, transportation, housing, and household supplies are an important part of every family's budget. However, when these expenses increase, managing monthly income becomes more challenging. Families may find that the same amount of money no longer covers everything it did a few years ago.
In 2026, household budgets can be affected by several factors, including changes in food prices, energy costs, transportation expenses, supply chains, and housing markets. The impact varies significantly between countries and even between cities within the same country.
Understanding why everyday essentials become more expensive is the first step toward managing household finances more effectively. By identifying the causes of rising expenses, reviewing spending habits, and making practical financial decisions, families can reduce unnecessary costs and protect their savings.
This guide explores the main reasons behind rising living costs and offers realistic strategies families can use to manage their money more confidently.
Why Are Everyday Essentials Getting More Expensive?
The cost of living refers to the amount of money people need to pay for basic goods and services. When the prices of these essentials increase, households must spend more to maintain the same standard of living.
Several factors can contribute to higher everyday expenses.
1. Rising Food and Grocery Prices
Food is one of the most important household expenses. Families regularly purchase products such as bread, rice, vegetables, milk, eggs, meat, cooking oil, and other necessities.
Food prices can rise because of poor harvests, extreme weather, higher fertilizer costs, fuel expenses, transportation disruptions, and changes in international commodity markets.
For example, if the price of cooking oil increases, a family may need to spend more on the same quantity of groceries. When several products become more expensive at once, the total effect on the monthly budget can be substantial.
What families can do: Compare prices across different shops, plan meals before shopping, use seasonal produce, and avoid purchasing large quantities of perishable food that may go to waste.
2. Higher Energy and Electricity Bills
Electricity, natural gas, heating, and cooling are essential for comfortable living. Changes in energy prices, weather conditions, taxes, and utility rates can increase monthly household bills.
During particularly hot or cold periods, families may also use more electricity to operate air conditioners, heaters, fans, and other appliances.
Energy costs can affect other expenses, too. Businesses often pay for electricity and fuel to manufacture, store, and transport products. When their operating costs increase, some of those expenses may eventually be reflected in consumer prices.
Practical ways to control energy consumption include:
Switching off lights and appliances when they are not needed.
Using energy-efficient bulbs and appliances when affordable.
Improving ventilation and reducing unnecessary heating or cooling.
Running washing machines with full loads when practical.
Checking electricity bills for unusual changes in consumption.
Small adjustments may produce useful savings over time, although the results depend on local energy prices and household habits.
3. Transportation and Fuel Costs
Transportation connects people with schools, workplaces, hospitals, shops, and other essential services. Rising fuel prices can increase the cost of driving, public transportation, delivery services, and commercial shipping.
Families that depend on private vehicles may face higher fuel and maintenance expenses. Meanwhile, households using public transportation may experience higher fares when operators face increasing costs.
Transportation expenses can also affect food and household products because goods must be moved from farms, factories, warehouses, and ports to stores.
To reduce transportation costs, families can combine errands into fewer trips, compare available public transportation options, maintain vehicles regularly, and consider carpooling when safe and convenient.
4. Housing and Rental Expenses
Housing is often one of the largest expenses in a household budget. Rent, mortgage payments, property maintenance, insurance, and utility charges can place significant pressure on family finances.
In some locations, rental prices rise because housing supply cannot keep pace with demand. Population growth, construction costs, interest rates, and local employment opportunities can also influence housing markets.
Families who cannot easily relocate may have limited options when rent increases.
Useful steps include reviewing housing expenses annually, discussing renewal terms with landlords when appropriate, reducing avoidable utility consumption, and considering total commuting costs before moving to a cheaper property.
A lower rent does not always mean lower overall expenses if transportation and other costs increase substantially.
5. Currency Fluctuations and International Supply Chains
Many countries depend on imported fuel, food ingredients, medicines, electronics, fertilizers, and industrial materials. When a local currency weakens against the currencies used to purchase these imports, imported products may become more expensive.
International supply chains can also be affected by shipping delays, trade restrictions, geopolitical tensions, extreme weather, and higher freight charges.
Businesses may respond by changing suppliers, adjusting prices, reducing product sizes, or absorbing part of the additional expense.
The effects are not identical everywhere. Countries with strong domestic production, diversified suppliers, or effective transport networks may experience different price changes from countries that depend heavily on imports.
How Rising Living Costs Affect Families
Higher prices affect households differently depending on their income, location, family size, and financial commitments.
Reduced Purchasing Power
Purchasing power describes how much people can buy with their available money. If income remains unchanged while essential prices rise, the same salary may purchase fewer goods and services.
Families may respond by choosing less expensive products, postponing purchases, reducing leisure activities, or changing their usual shopping habits.
Less Money for Savings
When a greater share of income goes toward necessities, less money may remain for emergency savings, education, retirement, or other long-term goals.
This can make households more vulnerable to unexpected expenses, such as medical bills, vehicle repairs, or temporary unemployment.
Greater Financial Stress
Financial pressure can affect sleep, family relationships, and overall well-being. Constantly trying to cover bills may leave people feeling uncertain about their future.
Creating a realistic budget and discussing financial priorities openly can help families understand their options and make decisions together.
10 Practical Ways to Reduce Household Expenses in 2026
Families do not have complete control over market prices, but they can often improve how they manage their available income.
1. Create a Monthly Household Budget
Start by calculating total monthly income after taxes and other necessary deductions. Then list essential expenses, including housing, groceries, utilities, transportation, healthcare, and education.
Separate these from flexible expenses such as entertainment, subscriptions, dining out, and nonessential shopping.
A simple budget makes it easier to identify spending patterns and decide where adjustments are possible.
2. Track Spending for 30 Days
Small purchases can become significant when repeated frequently. Keep a record of spending for one month, including cash purchases and digital payments.
At the end of the month, review the results and identify expenses that can be reduced without affecting important needs.
For example, unused subscriptions, frequent delivery fees, or unnecessary convenience purchases may offer opportunities for savings.
3. Plan Meals Before Grocery Shopping
Meal planning helps households purchase what they actually need rather than relying on last-minute decisions.
Before visiting a supermarket, check existing food supplies, prepare a shopping list, and plan meals around affordable ingredients.
Cooking at home can also reduce the cost of frequently purchasing prepared meals, although the savings depend on local prices, household size, and available time.
4. Compare Unit Prices
The cheapest-looking package is not always the best value. Compare prices per kilogram, litre, or individual item whenever the information is available.
However, buying in bulk is worthwhile only when the product will be used before it expires and the upfront cost fits the budget.
Families should also consider quality, storage requirements, and transportation costs when comparing offers.
5. Build an Emergency Fund Gradually
An emergency fund provides money for unexpected expenses without requiring immediate borrowing.
If saving several months of expenses seems impossible, begin with a smaller, achievable target. Set aside a fixed amount whenever income arrives, even if the amount is modest.
Over time, work toward saving enough to cover essential expenses for several months, adjusting the target to reflect job stability, dependants, health needs, and other circumstances.
Keep emergency savings accessible and separate from money intended for regular spending.
6. Review Recurring Bills
Review mobile phone plans, internet packages, insurance policies, bank charges, and digital subscriptions.
Compare alternatives carefully before switching. A cheaper service may have limitations, cancellation fees, or additional charges that reduce its value.
Contacting a provider to ask about available plans may also reveal a less expensive option.
7. Reduce Food Waste
Throwing away unused food means paying for products that provide no benefit.
Store food according to its requirements, freeze suitable items before they spoil, use leftovers safely, and rotate older products to the front of cupboards and refrigerators.
Planning meals around ingredients already available at home can reduce waste and the need for additional shopping trips.
8. Prioritize Essential Purchases
Before making a purchase, ask whether the item is necessary now, whether an existing item can serve the same purpose, and whether a less expensive alternative offers acceptable quality.
For larger purchases, comparing prices and waiting when practical can help prevent impulsive spending.
This does not mean avoiding every enjoyable purchase. A sustainable budget should leave some room for personal preferences when essential needs are covered.
9. Avoid High-Cost Debt
When living expenses rise, some families rely on credit cards, overdrafts, or short-term loans to cover the difference.
Borrowing may occasionally be necessary, but high interest rates and fees can make financial difficulties worse. Where possible, understand the full repayment amount before borrowing and prioritize reducing expensive debt.
If payments become difficult, contacting lenders early may provide access to repayment arrangements or other available assistance.
10. Review the Budget Every Month
Household expenses change with the seasons, school schedules, medical needs, and market conditions.
Review your budget monthly to identify changes and adjust spending limits. If income increases, consider directing part of the additional money toward emergency savings or debt repayment instead of automatically increasing discretionary spending.
The goal is not to follow a perfect budget. It is to build a system that can adapt to changing circumstances.
A Simple Example of a Household Budget
The following example uses illustrative monthly amounts in US dollars. It is not an estimate of average spending in any particular country.
Expense category | Monthly amount |
|---|---|
Housing | $900 |
Groceries | $400 |
Utilities | $150 |
Transportation | $200 |
Healthcare | $100 |
Education and childcare | $150 |
Debt payments | $100 |
Savings | $100 |
Personal and other expenses | $100 |
Total | $2,200 |
A family earning $2,200 per month might use this plan as a starting point, but its actual budget would depend on local prices, household size, income stability, and individual needs.
If grocery expenses increased by $40 per month, the family could review meal planning, compare unit prices, and reduce food waste before deciding whether to adjust another spending category.
The important principle is to respond to rising expenses deliberately rather than relying on guesswork.
Can Families Save Money Without Reducing Their Quality of Life?
Yes, in many cases. Saving money does not always require eliminating enjoyable activities or buying the lowest-quality products.
Families can focus on spending more efficiently by comparing prices, preventing waste, maintaining existing belongings, and selecting products that offer good long-term value.
For example, repairing a useful household item may cost less than replacing it. Preparing meals at home more often may reduce restaurant expenses. Sharing transportation can lower fuel costs while preserving access to work, education, and social activities.
However, not every expense can be reduced easily. Housing, essential medicines, childcare, and transportation may already represent the minimum practical spending required by a household.
When basic costs exceed available income despite careful budgeting, families may need broader solutions, such as seeking eligible public assistance, exploring additional income opportunities, negotiating bills, or obtaining advice from a qualified financial counselor.
The Role of Governments and Businesses
Household budgeting is useful, but rising living costs are not solely an individual responsibility.
Governments can influence affordability through housing policies, competition rules, infrastructure investment, taxation, targeted assistance, and measures that improve supply chains.
Businesses can help by improving operational efficiency, offering transparent pricing, reducing waste, and providing affordable product options where feasible.
Long-term improvements in productivity, competition, transportation, and energy efficiency can help reduce certain cost pressures. Nevertheless, the results depend on local economic conditions and the policies adopted.
Consumers should distinguish between temporary price changes and broader inflation trends. Inflation measures the rate at which the general price level changes; an individual product becoming more expensive does not necessarily mean that every price in the economy is rising at the same rate.
Frequently Asked Questions (FAQs)
1. Why are everyday essentials becoming more expensive in 2026?
Prices can rise because of inflation, higher production costs, energy expenses, transportation charges, supply disruptions, currency movements, and changes in consumer demand. The main causes vary by product and country.
2. What is the cost of living?
The cost of living is the amount of money required to pay for basic needs and maintain a particular standard of living in a specific location. It commonly includes housing, food, utilities, transportation, healthcare, and other essential expenses.
3. How does inflation affect family budgets?
Inflation reduces purchasing power when prices rise faster than household income. Families may need to spend more on necessities, reduce discretionary purchases, or save less.
4. What is the first step toward managing rising expenses?
Start by listing monthly income and expenses. Understanding where money goes helps identify which costs are essential, which are flexible, and where savings may be possible.
5. How can families reduce grocery bills?
Plan meals, compare unit prices, choose seasonal ingredients, use shopping lists, reduce food waste, and compare prices between reliable retailers.
6. Is buying groceries in bulk always cheaper?
No. Bulk purchases can offer better unit prices, but they may cause waste if food expires before use. They can also require more money upfront and additional storage space.
7. How can households lower electricity bills?
Reduce unnecessary energy use, switch off unused appliances, use efficient lighting, adjust heating and cooling sensibly, and review consumption for unusual increases.
8. Why do fuel prices affect grocery prices?
Fuel is used to transport food from producers to warehouses, markets, and stores. Higher transportation costs can increase the cost of delivering products, although the extent of any price increase depends on other market factors.
9. How much should a family save every month?
There is no universal amount. Families should first cover essential needs and required payments, then save what they can consistently afford. Even a small regular contribution can help build financial resilience.
10. How much money should an emergency fund contain?
A common long-term goal is three to six months of essential living expenses. However, people with irregular income, dependants, or limited access to assistance may need a different target. Starting with a smaller emergency reserve is still useful.
11. What should families do if their income does not cover essential expenses?
Review spending for genuine savings opportunities, check eligibility for assistance programs, contact creditors before missing payments, and explore realistic income options. If the shortfall continues, a qualified financial counselor or local support organization may help.
12. Can a family budget work when prices change frequently?
Yes. A budget should be reviewed regularly rather than treated as fixed. Updating grocery estimates, utility costs, and other changing expenses can help households respond to new circumstances.
13. Why is rent increasing in some cities?
Rental prices may rise when housing demand exceeds available supply. Construction costs, population changes, employment opportunities, interest rates, and local regulations can also affect rents.
14. How can families manage rising transportation expenses?
Combine errands, compare public transportation options, maintain vehicles properly, carpool where appropriate, and consider fuel efficiency when selecting a vehicle.
15. Are discounts always a good way to save money?
No. A discount only creates savings when the purchase is needed and the final price represents good value. Buying unnecessary products because they are on sale can increase total spending.
16. Should families stop all entertainment spending during inflation?
Not necessarily. A realistic budget can include affordable entertainment after essential needs and important financial commitments are covered. Free community events, libraries, outdoor activities, and home-based entertainment can provide lower-cost alternatives.
17. How do currency fluctuations affect household expenses?
When a local currency loses value against the currencies used for imports, imported goods may become more expensive. The effect depends on import dependence, exchange-rate changes, business pricing, and local competition.
18. Does a higher salary always improve purchasing power?
Not necessarily. If prices increase faster than salary, purchasing power may decline. What matters is how income changes relative to the cost of goods and services.
19. What is the difference between inflation and the cost of living?
Inflation measures changes in the general price level over time. The cost of living refers to the money needed to maintain a particular lifestyle in a particular place. Inflation can increase living costs, but household experiences vary.
20. How can families protect their financial future in 2026?
Maintain a realistic budget, build emergency savings gradually, avoid unnecessary high-cost debt, review recurring expenses, and work toward suitable financial goals. Regular reviews help families adapt as circumstances change.
Conclusion
Rising everyday expenses can make household financial management more difficult, especially when food, housing, energy, and transportation consume a growing share of income. Although families cannot control every market price, they can take practical steps to understand their spending and make informed decisions.
Creating a monthly budget, planning grocery purchases, reducing waste, reviewing recurring bills, and building emergency savings gradually can improve financial stability over time.
Most importantly, families should recognize that every household has different needs and limitations. The most effective financial plan is one that reflects actual income, local living costs, and essential responsibilities.
By combining realistic budgeting with consistent financial habits, households can become better prepared for unexpected expenses and navigate changing economic conditions with greater confidence.